Loading page content
Home insurance
Compare top carriers side by side in a few minutes, with your coverage explained in plain language. No sales calls, and a licensed agent reviews your policy before it's issued.
Now available in New Jersey · Hablamos Español · Falamos Português
Own a condo or rent out a property? See Condo insurance and Landlord insurance.
What home insurance covers
Four coverages make up most home insurance policies. Here's what each one does when something goes wrong.

Your home
Pays to repair or rebuild the house, and structures like a garage or fence, after damage from things such as fire, wind or a fallen tree.

Your belongings
Covers furniture, clothes, electronics and other belongings if they're stolen or damaged.

Liability
If someone is hurt on your property, or you accidentally damage someone else's, this pays their costs up to your limit.

Living expenses
If your home can't be lived in while it's repaired, this pays for a place to stay and the extra costs that come with it.
These are general descriptions. Your policy sets exactly what's covered. Flood and earthquake damage are not part of a standard home policy.
How your coverage is set
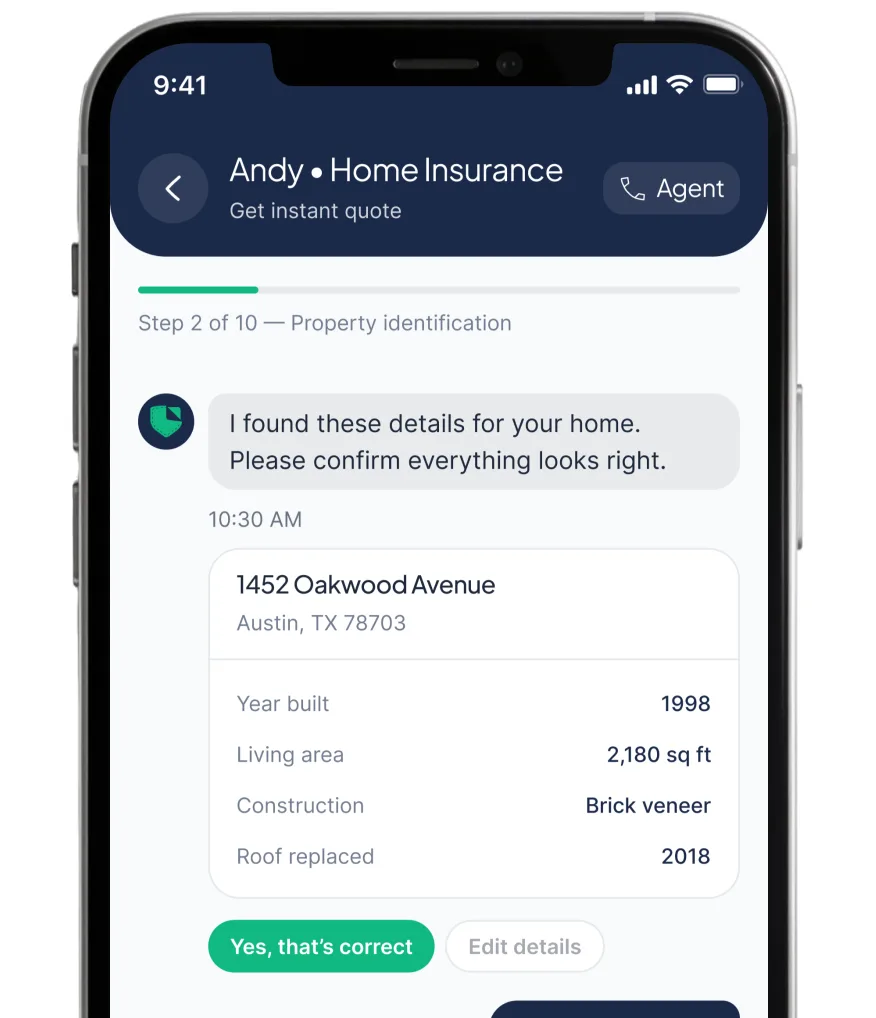
Home insurance is built around what it would cost to rebuild your house, which is usually different from what it would sell for. We estimate that from the details of your property, fill in what we can, and you confirm it. You don't have to guess at a number.
Your situation

Your lender needs proof of insurance before closing. Once your policy is issued, just ask and we send it to them directly.

If your insurance is paid through your mortgage, we bill your mortgage company for the new policy. Keep your old policy until the new one starts.

Quote both in the same chat. When your home and car are with the same carrier, many carriers lower the price on both.
Why PolicyPocket for home
Buying the policy is the easy part. Here's what we handle afterward.
01
When your mortgage company needs proof of insurance, ask us and we send it to them directly, so you aren't chasing paperwork.
02
Carriers often inspect a home or ask for documents in the first weeks of a policy. We follow those requests and walk you through them.
03
Home insurance renews once a year, and the price can change. When yours comes up, we check it against our other carriers and show you if there's a better price for the same coverage.
FAQ
Yes. Quotes are free, and there's no obligation to buy.
A few questions about the property, such as whether you have a dog, a pool or a trampoline. We fill in details about the house for you to confirm.
Yes. Tell us your closing date when you start. Once your policy is issued, we send proof of insurance to your lender on request. On a new purchase, lenders require the first year to be paid in full.
Yes. We bill your mortgage company for the new policy, and your old insurer will usually refund the unused part of your old one.
Yes. We can quote both together, and many carriers lower the price when both policies are with them.
No. Flood damage needs a separate policy.
It's free, it takes a few minutes, and you won't get a single sales call.
Quotes are estimates and subject to carrier underwriting.