Loading page content
Condo insurance
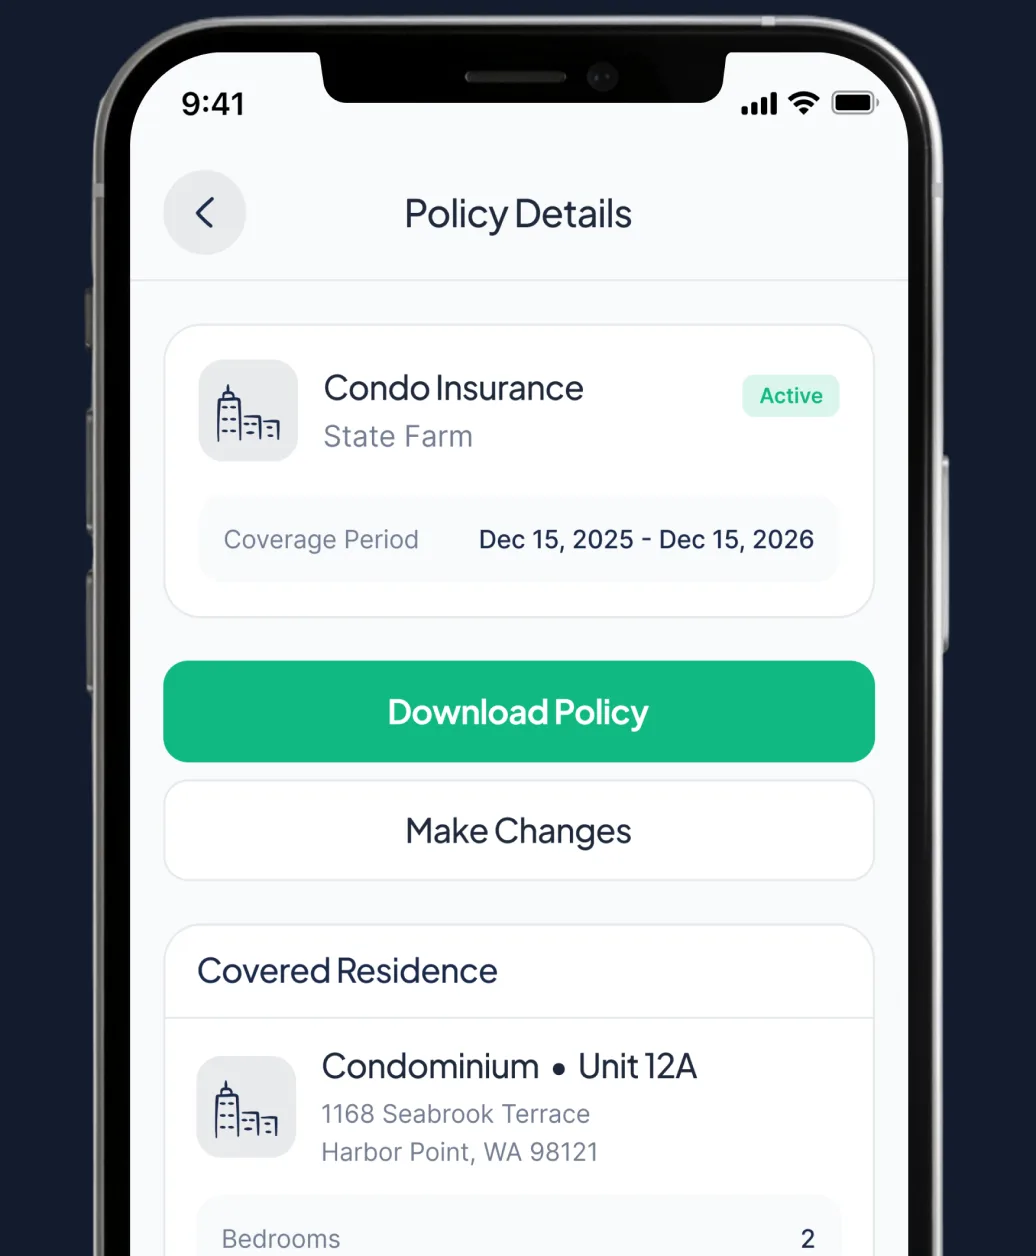
Compare top carriers side by side in a few minutes, with your coverage explained in plain language. No sales calls, and a licensed agent reviews your policy before it's issued.
Now available in New Jersey · Hablamos Español · Falamos Português
Own a house? See Home insurance. Renting out your condo? See Landlord insurance.
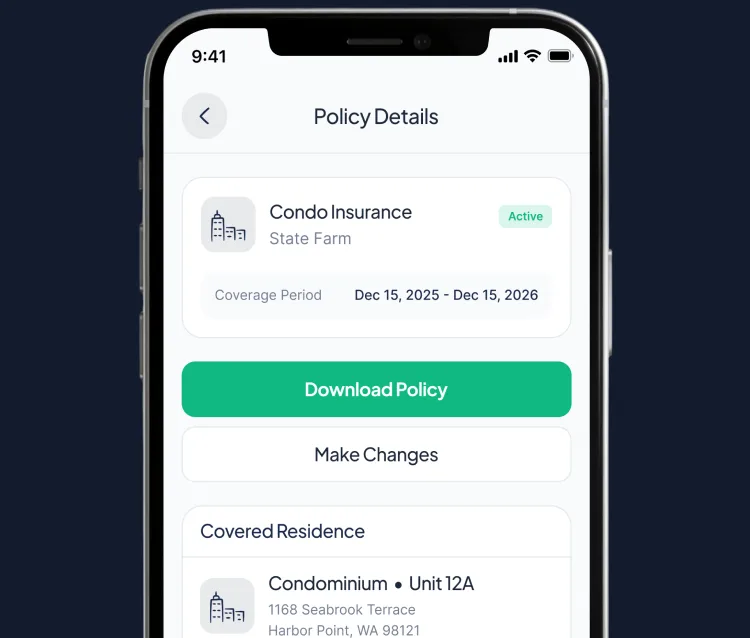
What condo insurance covers
Your association's insurance covers the building and shared areas. It usually stops short of everything inside your unit, and it never covers your belongings. Here's what a condo policy does.

Inside your unit
Covers the interior, such as floors, cabinets, fixtures and improvements you've made, after damage from things such as fire or a burst pipe.

Your belongings
How your coverage is set
Every association's insurance is different. Some cover only the bare walls, and others include the original floors and fixtures. Your policy picks up from there, so it helps to have a copy of your association's master policy handy when you start. Your property manager can give you one.
We set the coverage for the inside of your unit from the details of your property. You choose how much to cover your belongings, and Andy explains what each option means.
Your situation

Your lender needs proof of insurance before closing. Once your policy is issued, just ask and we send it to them directly.

Many associations require owners to carry their own policy. When yours asks for proof, tell us and we send it to them directly.

Quote both in the same chat. When your condo and car insurance are with the same carrier, many carriers lower the price on both.
Why PolicyPocket for your condo
Buying the policy is the easy part. Here's what we handle afterward.
01
When your lender or association needs proof of insurance, ask us and we send it to them directly, so you aren't chasing paperwork.
02
Carriers sometimes ask for documents or details in the first weeks of a policy. We follow those requests and walk you through them.
03
Condo insurance renews once a year, and the price can change. When yours comes up, we check it against our other carriers and show you if there's a better price for the same coverage.
FAQ
Yes. Quotes are free, and there's no obligation to buy.
The association's policy covers the building and shared areas. Your belongings, much of what's inside your unit, and any damage or injury you're responsible for are only covered by a policy of your own.
Ask your property manager for a copy of the association's master policy. A licensed agent can walk you through how your policy fits with it.
Yes. Tell us your closing date when you start. Once your policy is issued, we send proof of insurance to your lender on request. On a new purchase, lenders require the first year to be paid in full.
Yes. Your old insurer will usually refund the unused part. If your insurance is paid through your mortgage, we bill your mortgage company for the new policy.
Yes. We can quote both together, and many carriers lower the price when both policies are with them.
No. Flood damage needs a separate policy.
It's free, it takes a few minutes, and you won't get a single sales call.
Quotes are estimates and subject to carrier underwriting.
Covers furniture, clothes, electronics and other belongings if they're stolen or damaged.

Liability
If someone is hurt inside your unit, or you accidentally cause damage to someone else's property, such as water leaking into the unit below, this pays their costs up to your limit.

Living expenses
If your unit can't be lived in while it's repaired, this pays for somewhere to stay and the extra costs that come with it.

Association assessments
If your association bills owners for damage to shared areas that its own insurance doesn't fully cover, this can pay your share, up to your limit.
These are general descriptions. Your policy sets exactly what's covered. Flood and earthquake damage are not part of a standard condo policy.